Non-CDL Box Truck Insurance
Get Your Free Insurance Quote
Compare quotes from top carriers in minutes
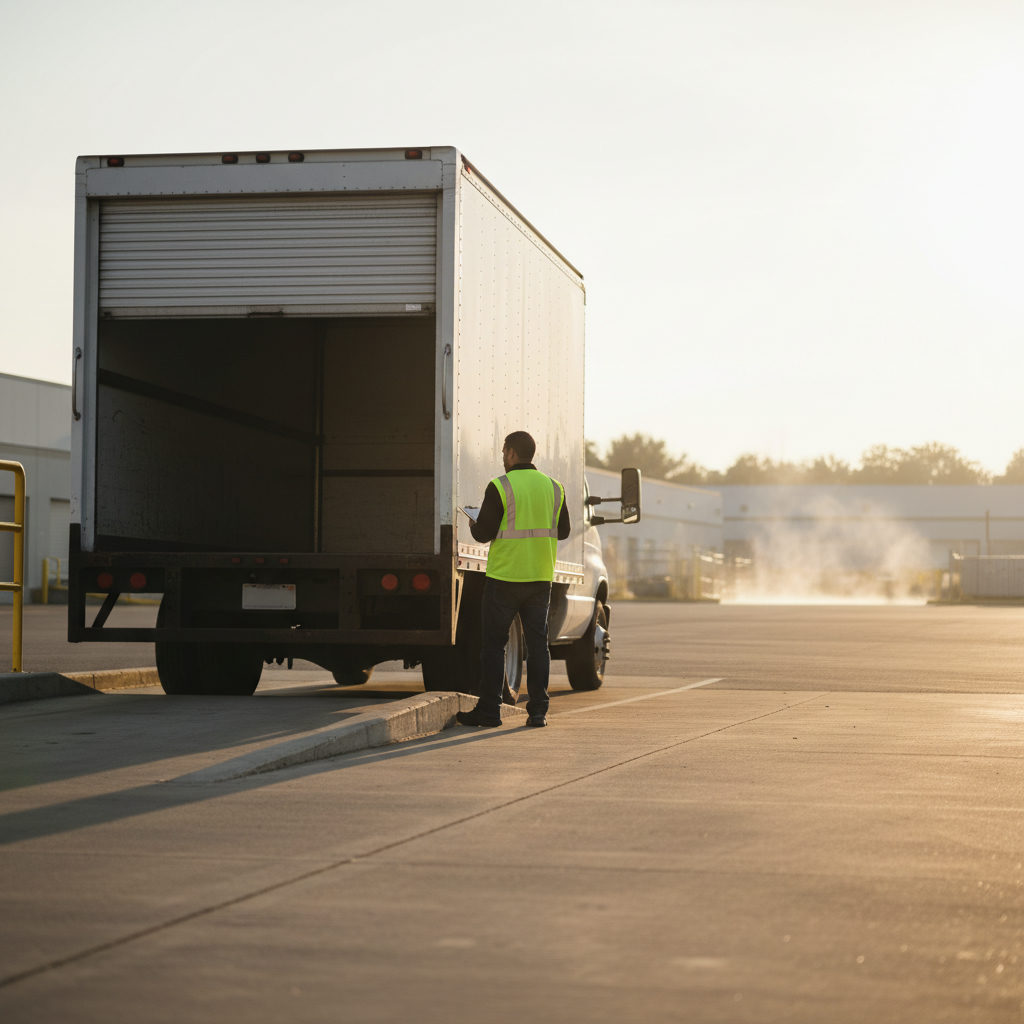
Non-CDL box truck insurance is still commercial insurance: not needing a CDL answers a licensing question, and a box truck used for business still needs a commercial policy. This guide covers what non-CDL status changes for box truck insurance, what your operation needs, what sets the price, and the mistakes that leave a truck uninsured.
Start My Free Quote. Prefer to talk? Call (864) 883-9477.
What Makes a Box Truck Non-CDL
Two weight lines matter, and they do different jobs.
| Line | What it decides | Rule |
|---|---|---|
| 26,001 lbs | Whether the driver needs a CDL. The rating or the actual weight counts, whichever is greater | 49 CFR 383.5 |
| 10,001 lbs | Whether federal safety rules and a USDOT number apply to interstate work. The rating or the actual weight counts, whichever is greater | 49 CFR 390.5T |
So a truck rated under 26,001 lbs can still need a CDL driver if it is loaded past that weight.
A lighter truck can also need a CDL for other reasons:
- It hauls hazardous materials in an amount that needs placards.
- It is designed to carry 16 or more people, including the driver.
- It tows a trailer rated or loaded over 10,000 lbs, and the combination reaches 26,001 lbs or more.
On sizes, three things to know:
- Box length does not decide the rating. The chassis does.
- Check the label on the driver's door frame for the GVWR. A 26-foot box truck is often built to sit just under 26,001 lbs, but some are rated higher.
- A liftgate or a reefer unit adds weight and narrows the margin under 26,001 lbs.
For the licensing rules in full, see do you need a CDL for a box truck.
Does a Non-CDL Box Truck Need Commercial Insurance?
Yes, if it is used for business. Personal auto policies usually exclude business use, so a claim from a work trip may be denied. Box truck insurance without a CDL is still a commercial policy, and it should be matched to how the truck is actually used.
Non-CDL Box Truck Insurance Requirements by Operation
Federal requirements follow the truck's weight, what you haul, who you haul for and where you run. CDL status is not part of the test.
| Operation | Federal requirement |
|---|---|
| For-hire, interstate, truck rated 10,001 lbs or more, non-hazardous freight | $750,000 liability (49 CFR 387.9). USDOT number and operating authority. Your insurer files proof with FMCSA |
| For-hire, interstate, every truck in the fleet rated under 10,001 lbs, non-hazardous freight | $300,000 filing minimum for operating authority (49 CFR 387.303T) |
| Private carrier, hauling your own non-hazardous goods | No federal minimum. State requirements may apply. A USDOT number is still needed for interstate work at 10,001 lbs or more |
| Intrastate only | State rules. Some states require their own filing or a USDOT number |
| Leased to a motor carrier | The carrier usually provides primary liability while you are under its dispatch. You usually need your own non-trucking liability for trips off dispatch |
Hazardous materials carry higher federal minimums, for private carriers as well as for-hire.
Contracts add their own layer. Brokers and shippers often ask for $1,000,000 in auto liability and set their own cargo limit. That is a contract term, not law.
On filings: for a for-hire interstate carrier, the insurer files a BMC-91 or BMC-91X with FMCSA as proof of liability coverage. For limits and filings scenario by scenario, see box truck insurance requirements.
Know your operation? Get your box truck quote. Start My Free Quote. Prefer to talk? Call (864) 883-9477.
Coverage a Non-CDL Box Truck Usually Carries
| Cover | What it does | Usually needed when |
|---|---|---|
| Auto liability | Injury and damage you cause using the truck, including most loading and unloading claims | Always |
| Motor truck cargo | Freight you haul for others | Hauling for hire |
| Physical damage | Your truck. Check whether it is valued at actual cash value or a stated amount | Financed or valuable trucks |
| General liability | Business claims not tied to using the truck | A contract asks for it |
| Hired and non-owned auto | Liability in rented or borrowed vehicles | You rent trucks or staff use their own cars for work |
| Non-trucking liability | Liability for off-dispatch use | Leased to a carrier |
| Uninsured or underinsured motorist | Your injuries when the other driver lacks enough cover | Required in some states |
For what each cover usually pays on a box truck, see box truck insurance coverage. For the covers we place, see coverages offered.
Drivers, Helpers and Hiring
A non-CDL truck widens the pool of drivers you can hire. Underwriters still look at each one.
- What they check. Each driver's motor vehicle record, experience in similar trucks, and age. Thresholds vary by insurer.
- Before anyone drives. Every driver should be listed on the policy before they take the truck out.
- Helpers and employees. Workers compensation rules vary by state. An owner working alone can check for occupational accident cover.
Non-CDL Box Truck Insurance Cost
No single figure fits. The premium is built from the covers you choose, and liability is usually the largest part. Not needing a CDL does not lower the price on its own. These are the factors that usually move it:
| Factor | Why it moves the price |
|---|---|
| Operation | For-hire interstate work carries more exposure than private local delivery |
| Radius and stops | More miles and frequent city stops mean more exposure |
| Cargo | Its value and how often that kind of freight is stolen |
| Truck value | Sets the physical damage premium |
| Limits and deductibles | Higher limits cost more. Higher deductibles shift cost to you |
| Time in business | A new venture has no history to price |
That is why 26-foot box truck insurance for a for-hire regional run and a policy on a small private delivery truck can land far apart. For published figures and what sits behind them, see box truck insurance cost. For a starting estimate for your own setup, try the Instant Rate Estimator.
When a Non-CDL Operation Crosses Into CDL Territory
Any of these can put a truck or a driver on the CDL side of the line:
- A heavier replacement truck.
- Loads that take the actual weight to 26,001 lbs or more.
- Adding a heavy trailer.
- A load of hazardous materials that needs placards.
- A vehicle built to carry 16 or more people, including the driver.
Tell your insurer before the change, not after. The drivers, trucks and operation on the policy should match the work you actually do.
Mistakes That Leave a Non-CDL Box Truck Uninsured
| Mistake | What happens |
|---|---|
| Using a personal policy for business work | Claims may be denied |
| Quoting as private while hauling for hire | Coverage and filings may not match the work |
| Drivers not listed | Claims involving them may not be covered |
| Declared radius smaller than the real one | Can cause coverage disputes or repricing |
| Certificate limits below the contract | Loads may not be tendered to you |
| Letting the policy lapse | Can put operating authority at risk once the cancellation takes effect |
What to Have Ready for a Quote
- VIN and GVWR for each truck.
- For-hire or private, and interstate or intrastate.
- Your radius and garaging address.
- What you haul and what it is worth.
- Details for every driver.
- The insurance requirements in your contracts.
- Your USDOT number and authority status, if you have them.
For what else we ask for, see truck insurance quotes.
Frequently Asked Questions
Get Box Truck Cover That Fits How You Run
The CDL line decides who can drive the truck. How you use it decides the insurance.
Start My Free Quote. Prefer to talk? Call (864) 883-9477.
Continue reading
- Box truck insurance
- Compare truck insurance quotes
- Trailer Interchange Insurance Massachusetts: Cost Guide
- Semi Truck Insurance for New Drivers: Where to Start
- 18 Wheeler Insurance Policy Limits: 2026 Guide
- Coverages we offer for owner-operators & fleets
- Common questions about trucking insurance
Ready to compare rates? Get a free trucking insurance quote from carriers built for insurance tips.
Ready to Get Started?
Get personalized insurance quotes tailored to your business